All Categories
Featured
Table of Contents
This is specifically real with debt settlement. You might send cash to a debt settlement business for numerous years before finding out your financial institutions will not negotiate with them. With the exception of some nonprofits, there will be a fee for debt relief. This consists of company charges for services or financing products, attorneys' costs for personal bankruptcy, and even nonprofit therapy firms that often charge a cost for facilitating your month-to-month payments.
These charges are particularly an issue when it comes to financial obligation settlement, but could be evaluated at any time you miss a monthly financial obligation payment. If you have actually financial obligation forgiven, it might be thought about gross income. If so, the creditor who forgives the financial obligation will send you a 1099-C detailing how much the initial debt was and just how much was forgiven.
Even if you ultimately settle or get the financial obligation dismissed, a record of the event will stay on your credit reports for 7-10, and can make it tough to get approved for loans at affordable rates in the near future. In summary, there are a number of ways to get relief, and each has its own advantages and disadvantages.
You may choose to manage financial obligation relief yourself, but working with a professional might cause more choices for restructuring or decreasing your debt. Working with a nonprofit credit therapy company suggests having a professional to direct you through all your choices for debt relief. A credit counselor can analyze your unique scenario your budget, credit rating and more to make customized suggestions for a service.
Credit counselors get and maintain professional accreditations. These personal financing experts can teach you the basic abilities to decrease financial obligation and manage your expenses. Credit therapy firms do not specialize in quick-fixes. They often use a suite of services, readily available through a series of phone or in-person appointments, that are suggested to assist customers prevent financial emergencies, handle debt, build credit, achieve monetary stability and more.
2026 Financial Recovery Programs: Guide
Ensure you discover a trusted credit counseling company to assist in your debt relief journey. Credit therapists intend to use the very best financial advice based on all of the information you share. That implies the recommendations you get might not be what you wanted. A credit counselor must present you with a clear strategy, but it might take more time and effort than you anticipated to reach your goal.
The end-goal of being debt-free is most likely worth it, however some consumers lose perseverance and leave before they get rid of all their financial obligation. To enroll in a debt management program, you'll initially need to be screened by a credit therapist. Based on your particular lenders, your financial obligation balances, and other information like whether or not you're current on your payments, you might be qualified to enroll in a debt management program.
Here's what you must consider up-front: You'll make one month-to-month payment to the therapy firm that will then be dispersed to your financial institutions in agreed upon terms. A financial obligation management program can save you from harming your credit by preventing missed payments. Plus, your ratings will enhance as you pay down debt balances over time.
Under a DMP some of your financial institutions might accept minimize your monthly payment quantity, minimize your rates of interest, or forgive particular fees. Financial obligation management programs usually take 3-5 years to complete. The counseling firm typically charges an enrollment and upkeep charge to assist cover the expense of their services, consisting of processing your payments.
Mastering Your Debt Relief Plans in 2026
That might include an increase in your interest rates or monthly payments, or reinstated late costs. If you're required to close your credit accounts under a debt management strategy, you'll likely see an instant drop to your credit ratings.
Effective Debt Management Strategies to Reduce DebtThe goal of financial obligation combination is to make financial obligation payment more affordable or more manageable. However this option has its own threats and rewards:. You could utilize a credit card or a personal loan to consolidate financial obligation, by obtaining a new account through your bank, cooperative credit union or otherwise.
You might have the ability to get a lower rate of interest when you secure a new loan to combine, particularly if your credit report have actually enhanced or if you've settled a substantial amount of your initial financial obligation balances. Not just do lower rates save you money however they can also help you pay off debt quicker.
How to Seek 2026 Financial Relief Help Immediately
Some loans require collateral, such as your home or car. A security loan may include lower rates, but you'll risk losing your property if you fall back on the payments. Financial obligation settlement involves working out with creditors to pay less than the total you owe. You can attempt to make these negotiations yourself, or deal with a financial obligation settlement company that works out in your place.
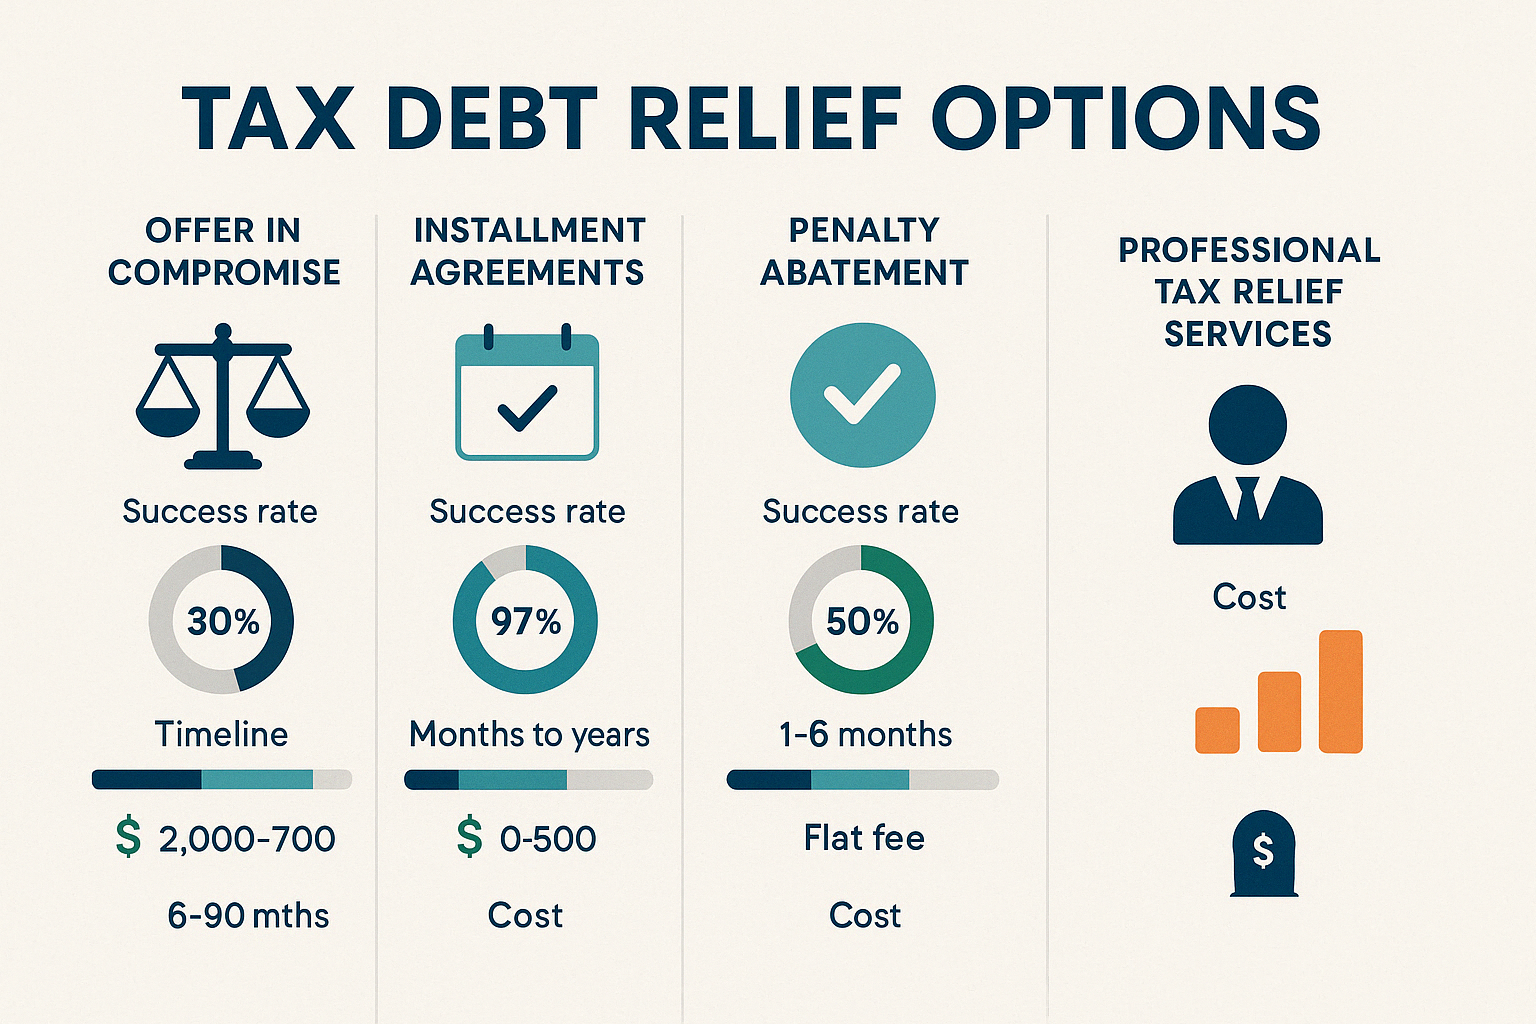
This can be an incredibly risky solution for dealing with debt, so it is very important to comprehend the benefits and drawbacks: You'll acquire charges from your creditors and from the financial obligation settlement company, but there's a possibility of conserving cash when it's all over with. While some financial institutions won't work out a settlement, others may accept a lump amount for as little as 50% of what you owe.
That might seem like forever, but for some debtors this could indicate being debt free faster than if they settled their full financial obligation balances on their own. A number of customer advocacy agencies caution individuals versus utilizing financial obligation settlement, consisting of the Federal Trade Commission (FTC) and the Customer Financial Defense Bureau (CFPB).
Is 2026 the Right Time for Credit Resolution?It can take as much as 3 years or more to conserve up enough money for settlement offers, many clients end up dropping out of their financial obligation settlement program before they have actually settled their debts. Financial obligation settlement can harm your credit rating simply as much as filing bankruptcy, and settled financial obligations will remain on your credit reports for seven to 10 years.
Financial obligation settlement business declare they can get as much as 70% of your credit card debt forgiven, however the truth is that your financial institutions may refuse to work with a debt settlement business. The IRS requires you to report forgiven debt of $600 or more as gross income, so you might have to pay more taxes after financial obligation settlement.
Is Debt Relief Right Choice in 2026?
The suit might result in wage garnishment or frozen savings account. In addition to debt settlement, there may be other methods to have a few of your financial obligation forgiven. This consists of programs like the Department of Education's Public Service Loan Forgiveness Program, or other unique choices from lending institutions who forgive debt due to financial difficulties.
Here are some of the pros and cons of going this route: If you receive a genuine loan forgiveness program, you could take advantage of having financial obligation forgiven. You'll likely still have to pay some of it back, but the cost savings could be a big financial help. Debt forgiveness rip-offs have actually ended up being increasingly common given that the pandemic, especially student loan scams.

Latest Posts
Effective Strategies to Manage Debt
Strategic Tips for Consolidating High-Interest Debt
Proven Ways to Reduce 2026 Credit Card Debt