All Categories
Featured
Table of Contents
Here's a breakdown of some of the most popular ones to think about: This method starts by noting your debts from tiniest to biggest. Make minimum payments on all your cards while transporting any additional funds towards the tiniest balance. As soon as you pay off the tiniest financial obligation, you'll move on to the next smallest and gain momentum with each victory.
It takes longer to pay off high-interest debts. Those focused on quick wins and staying determined Focus on paying off the debt with the highest interest rate.
Those concentrated on decreasing overall interest paid and quicker general debt reduction. This method integrates your card debts into a single loan with a lower interest rate. It can simplify your payments and save you money on interest charges. There are two main alternatives: A individual loan is not backed by security, and approval depends on your creditworthiness.
The application procedure is possibly faster than that of guaranteed loans. It requires excellent credit to qualify, and rate of interest are usually higher than those for safe loans. Those with excellent credit who prefer the simplicity of a single payment. A home equity loan usages your home's worth as security and can result in a lower rate of interest.
This choice may use lower rate of interest than charge card. Consolidating multiple debts can likewise streamline monthly payments. Unsecured loans usually require excellent credit to qualify. A home equity loan puts your home at risk if you fail to pay back. This method is perfect for individuals with great credit who prefer the simpleness of a single regular monthly loan payment.
The Shift From Aggressive Settlement to Strategic Management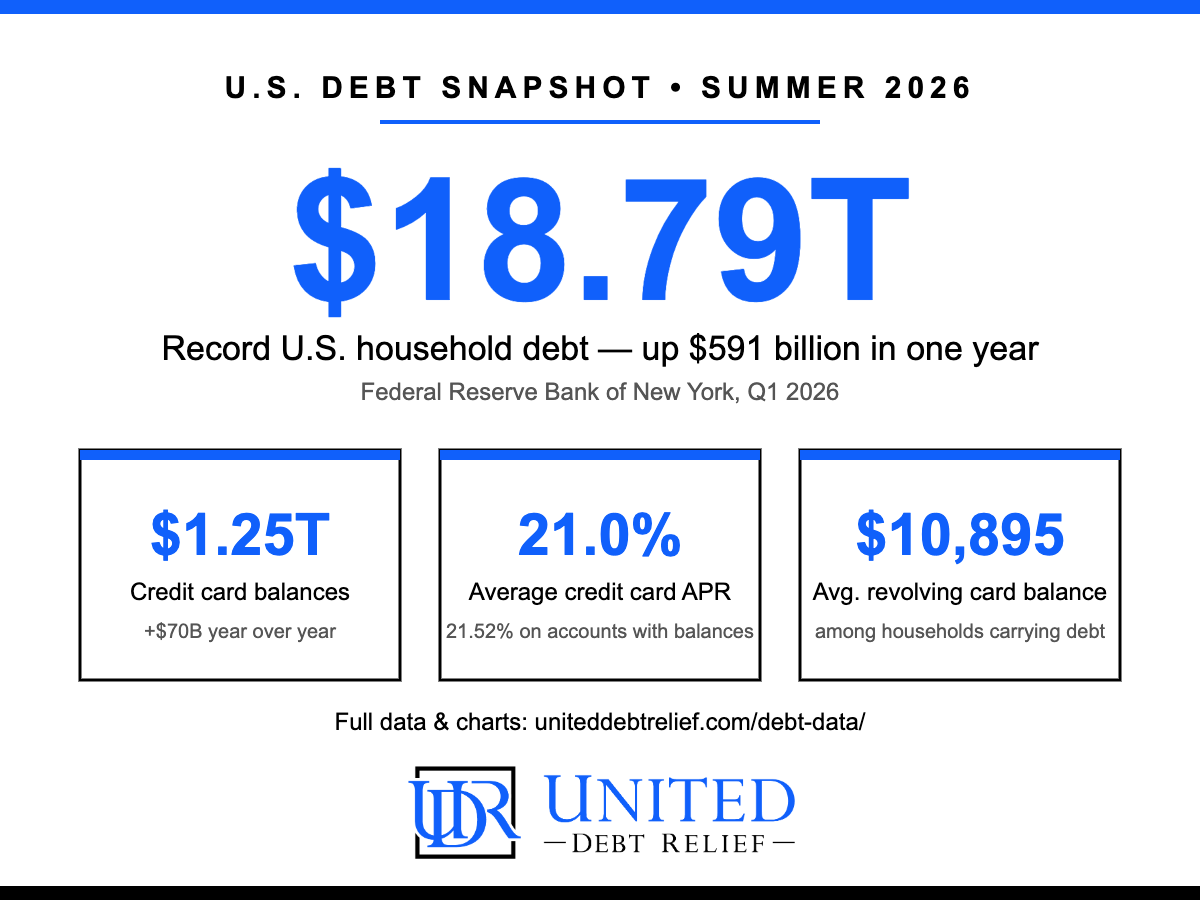
Seeking 2026 Financial Hardship Relief
Several other additional techniques can lower credit card debt tension: While the minimum payment keeps your account in good standing, it won't considerably decrease your financial obligation. Paying even a little additional every month will reduce the amount you owe faster. If possible, set up automatic payments above the minimum to make the procedure simpler.
This can produce a vicious cycle of debt that's tough to leave. Consider keeping a couple of cards locked away or temporarily decreasing your credit line as you restore healthy spending habits. Developing a comprehensive budget plan assists you track where your cash goes, exposing locations where you can cut down. This will maximize more funds to remove your debt.
A credit counseling course can offer important assistance if you discover it difficult to manage multiple credit cards properly. If you're having a hard time, get in touch with the credit card provider and discuss your scenario.
These services can be valuable if managing financial obligation is frustrating or you need professional aid creating a repayment technique. One of the fastest ways to tackle debt is to make more money.
You've paid off your credit cardnow what? Now that you've paid off your credit card, you may wonder about your next steps.
Finding 2026 Financial Hardship Help
Even if you do not plan on utilizing the card regularly, keeping it open for emergency situation expenses might be beneficial.
Simply be mindful that it can momentarily reduce your credit rating. You can use the funds to pay down other debts faster.
Rerouting credit card payments to savings can supplement your funds for vacations, big purchases, or emergency funds. Credit bureaus monitor this metric to examine your credit usage.
Effective Debt Management for Over-Leveraged Families
This budget plan can enable you to pay off your monthly balance if you continue utilizing your credit card. If you're struggling to remain within your budget plan, consider designating your charge card for emergencies just. This can help prevent a high balance and keep your finances in check. Comprehending the length of time to pay off a credit card can help you make the essential way of life changes to reach your goal.
Analyze your spending practices and try to find locations to cut back. Even little modifications with time can produce space in your budget for financial obligation repayment. Watch out for services that guarantee to rapidly eliminate your debt or significantly settle it for a portion of what you owe. These frequently end up being scams.
The Shift From Aggressive Settlement to Strategic ManagementThis will only include more potential for costs and make the process harder. When utilized properly, credit cards can considerably enhance your credit rating. They likewise reveal the world you're liable and take your financial health seriously. Managing credit card financial obligation can be a substantial financial challenge. Exploring charge card options may offer the relief and control you need to regain your financial footing.

Devoting yourself to a method is the essential to getting out of credit card financial obligation quickly. We can't make your monthly credit card payments for you (really, we kind of can with a personal loan), but we can reveal you how to get out of credit card debtfast!
If you have a $350 balance on a credit card with a 21-percent annual rates of interest, and you make a minimum payment of only $20 every month, it will take you 22 months to pay it off. That's nearly two years. If you double your payment to $40, you'll have the card settled in just 10 months.
How to Lower Credit Card Debt in 2026
This technique becomes much more valuable when you use it to even bigger balances. Say you are making the minimum $90 payment on a card with a $2,750 balance and a 21 percent interest rate: You'll discover yourself paying for the next 45 months (or 3.75 years). If you double the monthly payment, you'll be out of financial obligation in only 18 months (1.5 years).

Latest Posts
Effective Strategies to Manage Debt
Strategic Tips for Consolidating High-Interest Debt
Proven Ways to Reduce 2026 Credit Card Debt