All Categories
Featured
Table of Contents
Here's a breakdown of a few of the most popular ones to consider: This technique begins by listing your debts from smallest to largest. Make minimum payments on all your cards while channeling any extra funds towards the smallest balance. As soon as you pay off the tiniest debt, you'll carry on to the next smallest and acquire momentum with each success.
It takes longer to pay off high-interest debts. Those focused on fast wins and staying determined Focus on paying off the financial obligation with the greatest interest rate.
Those concentrated on minimizing total interest paid and quicker overall financial obligation reduction. This technique integrates your card debts into a single loan with a lower interest rate. It can simplify your payments and conserve you cash on interest charges. There are two main choices: A individual loan is not backed by collateral, and approval depends upon your creditworthiness.
The application process is potentially faster than that of secured loans. It needs excellent credit to certify, and interest rates are typically greater than those for secured loans. Those with good credit who choose the simplicity of a single payment. A home equity loan uses your home's value as security and can result in a lower rates of interest.
This alternative may provide lower interest rates than credit cards. Unsecured loans typically require excellent credit to qualify.
Are You Eligible for Improved Debt Management Program Terms?
Reviewing the Top 2026 Debt Relief Plans
Nevertheless, a number of other extra methods can decrease charge card debt tension: While the minimum payment keeps your account in good standing, it will not considerably reduce your financial obligation. Paying even a little extra monthly will lower the amount you owe much faster. If possible, set up automated payments above the minimum to make the procedure simpler.
This can develop a vicious cycle of financial obligation that's tough to leave. Consider keeping a couple of cards locked away or temporarily decreasing your credit limitations as you reconstruct healthy spending habits.

A credit therapy course can offer important assistance if you find it challenging to handle several credit cards responsibly. These courses offer pointers and techniques for budgeting, financial obligation reduction, and accountable credit use. Abiding by a financial obligation management plan can set you up for long-lasting monetary success. If you're struggling, call the credit card issuer and explain your circumstance.
These services can be valuable if handling debt is overwhelming or you need expert aid producing a payment technique. One of the fastest methods to deal with debt is to make more cash.
You've settled your credit cardnow what? Congratulations on satisfying one of your financial objectives! You're most likely questioning what you need to do next. We have some terrific concepts and pointers to assist you navigate your next actions. Now that you've settled your charge card, you may question your next steps.
Smart Ways to Slash Credit Card Rates
Even if you don't plan on using the card routinely, keeping it open for emergency situation expenditures could be beneficial.
Just be aware that it can briefly decrease your credit score. You can use the funds to pay down other debts faster.
Rerouting credit card payments to cost savings can supplement your funds for trips, large purchases, or emergency situation funds. Credit bureaus monitor this metric to evaluate your credit use.
Top Debt Management Strategies to Reduce Debt
This spending plan can enable you to settle your regular monthly balance if you continue using your credit card. If you're having a hard time to remain within your budget, think about designating your credit card for emergencies just. This can assist prevent a high balance and keep your finances in check. Comprehending the length of time to settle a credit card can assist you make the required lifestyle modifications to reach your goal.
Even small modifications over time can develop room in your spending plan for debt repayment. Be cautious of services that guarantee to rapidly erase your debt or drastically settle it for a portion of what you owe.
The Changing Face of Debt Relief in 2026When used responsibly, credit cards can substantially improve your credit score. Managing credit card debt can be a considerable financial difficulty.
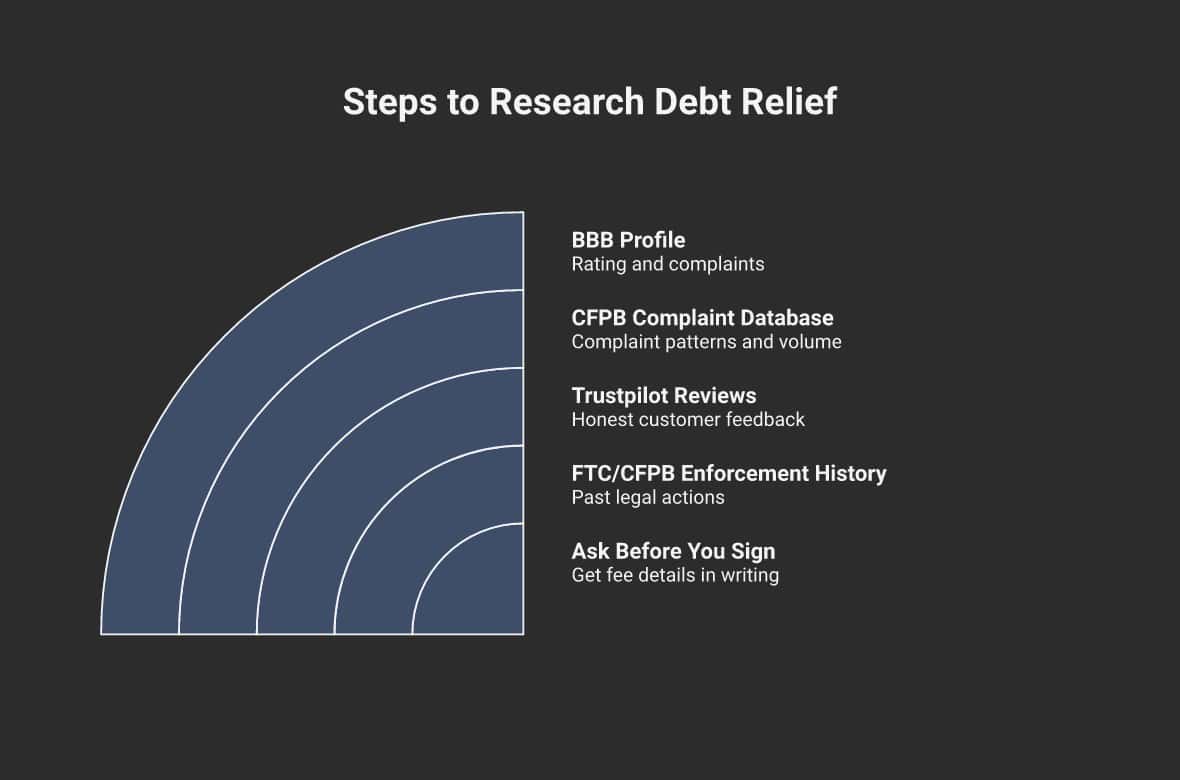
Devoting yourself to a method is the crucial to getting out of credit card financial obligation quickly. When you adhere to your objective, your commitment equates into an overarching way of life where you no longer need to concern yourself with tackling your credit card payments on a monthly basis. We can't make your month-to-month credit card payments for you (in fact, we kind of can with a personal loan), but we can show you how to get out of credit card debtfast! Keep reading to find out about the leading 4 methods to pay off your charge card in the quickest manner possible.
If you have a $350 balance on a charge card with a 21-percent annual rate of interest, and you make a minimum payment of only $20 monthly, it will take you 22 months to pay it off. That's practically 2 years. If you double your payment to $40, you'll have the card paid off in only 10 months.
Analyzing the Top 2026 Debt Relief Plans
This method ends up being even more important when you use it to even larger balances. State you are making the minimum $90 payment on a card with a $2,750 balance and a 21 percent rate of interest: You'll find yourself making payments for the next 45 months (or 3.75 years). If you double the monthly payment, you'll be out of debt in just 18 months (1.5 years).

Latest Posts
Effective Strategies to Manage Debt
Strategic Tips for Consolidating High-Interest Debt
Proven Ways to Reduce 2026 Credit Card Debt